Regulatory Compliance
How accountants can help business clients think more strategically about cash savings
When you ask business clients if their deposits are protected against bank failure, most finance directors will immediately answer “yes”. Kate Toumazi, CEO of Insignis, explores the questions on what further reassurance is needed besides using a regulated bank, a long‑standing relationship, and the well‑known name of their institution?
In a survey of 500 senior finance and business leaders, 96% said they believed their deposits were protected. Yet two thirds either had no meaningful awareness of how the Financial Services Compensation Scheme (FSCS) deposit protection applies to their business holdings, nor couldn’t correctly identify what it covers. Fewer than four in ten could name the current protection limit, which was updated last December.
For accountants, that gap between confidence and knowledge is where an important conversation should start, and an opportunity to add value seized.
Dan French,
founder and CEO, Consider Solutions
The future that is unfolding isn't one where finance and accounting professionals are replaced – but one where their responsibilities will change. Success in this transition depends on making clear assessments of where AI will add value, establishing clear policies and governance in use, and the cultivation of skills that complement technical capabilities.
ACCA expects that coming years will see organisations develop more integrated workflows based on the principle that AI adoption is not just about distinguishing high versus low-value activities – but focusing on outcomes, quality and value.
Only a minority of finance and accounting teams have implemented AI solutions – but these resources are widely available, and organisations are reviewing opportunities and workforce needs.
AI adoption is expected to accelerate in coming years, especially as our data shows investment on AI initiatives is increasing, and widespread cloud adoption provides a crucial foundation for AI implementation.
The profession is still in the invention and adoption stage of AI, as demonstrated by investment data and current adoption/usage statistics. And the profession is embracing the learning and employment challenge offered by AI as shown by the recently announced changes to the ACCA Qualification which embraces emerging advances in technology and sustainability.
The report adds that widescale use of a general-purpose technology, like AI, may take longer than anticipated.
Dr Jeremy Osborn, FCMA, CGMA, FCPA (Aust.), Global Head of Sustainability, Chartered Institute of Management Accountants (CIMA)
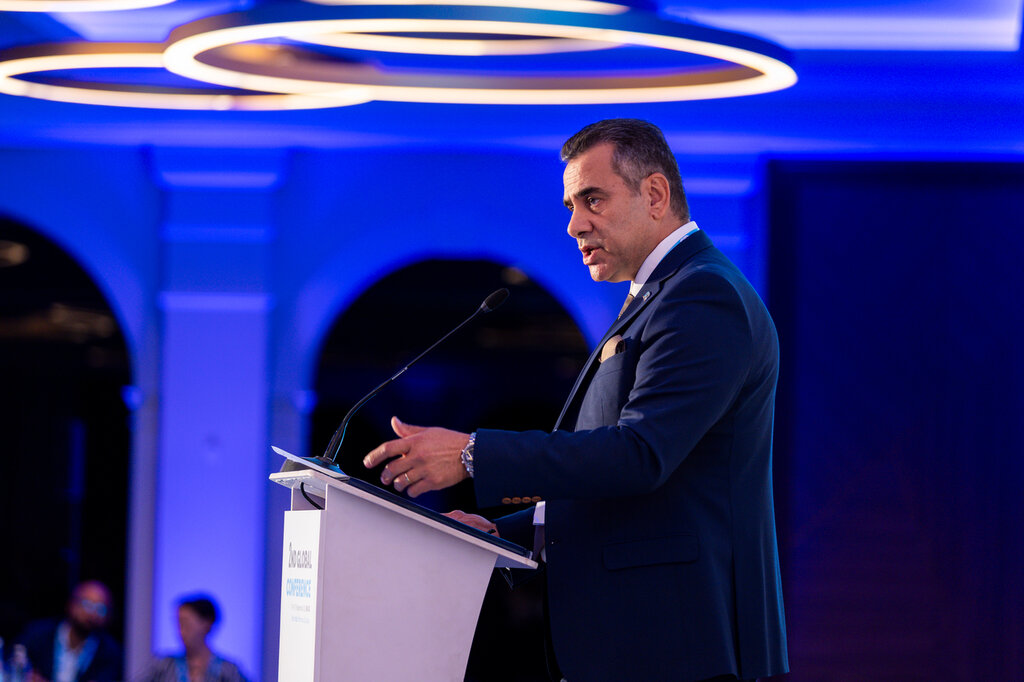
Christos Christodoulou, CEO, Delphi Alliance
"Combined global turnover is not the metric by which we measure success," states Christos Christodoulou, founder and CEO. "What matters is how effectively we collaborate to support our clients - and our growing presence on the geopolitical stage. Reaching IAB Top 20 in four years was a fantastic recognition, but even more importantly, it signals that the industry is beginning to acknowledge that the future of professional services isn't about size alone. It's about the depth and breadth of what you can deliver."
Finance leaders lack FSCS awareness
FSCS deposit protection covers cash holdings up to £120,000 per UK-authorised banking license for eligible businesses. One in three businesses currently hold over £1 million with a single bank, which is over eight times the protection limit.* Even among businesses with multiple banking relationships, three quarters still hold more than the protection limit at their primary bank.
It’s also worth pointing out that while some larger businesses might not be eligible for FSCS protection, leaving large sums of cash in a single account still exposes businesses to significant concentration risk should their bank fail or restrict access. Apply that exposure to a national scale, and it quickly adds up to millions across businesses up and down the country – making it, in turn, a bigger topic for you to discuss with your business clients.
This is also where offering advisory services can make a genuine difference. Reviewing where your clients’ cash sits, whether balances exceed the protection limit at any single institution, and whether funds are spread across banks holding separate banking licenses, is practical, actionable advice with real consequences for clients if something goes wrong.
Cash returns aren’t being optimised
Protection aside, there’s a straightforward returns problem that is easier to solve than most businesses realise.
The research shows that the average business in our survey holds £2.21 million in cash. The average interest rate UK businesses were earning on that cash, based on Bank of England data, was 1.61%. Competitive rates for business savings are available at 3.5%. For a business holding the survey average, the gap between those two figures represents around £42,000 in additional missed interest every year. That’s roughly the full cost of your business clients employing an additional member of staff for a year, or covering the costs of your advisory fees.
Here too, you are well-placed to provide guidance to clients about how to optimise returns by moving funds into higher interest accounts. In a challenging trading environment, with tighter margins and increased costs associated with hiring and borrowing, this should be a no-brainer for any business with significant cash holdings.
The admin burden no-one is measuring
There is also another cost associated with poor cash management – one that won’t appear on balance sheets.
Senior leaders in our survey spend an average of 4.5 hours per week managing banking relationships. For CFOs specifically (4.3 hours per week), that is over a month’s worth of time spent contacting banks, resolving issues and monitoring accounts across multiple portals every year. This is not strategic work, but administrative friction that falls disproportionately on the people whose time is most valuable to their organisations.
If you already have oversight of a client’s broader financial position, this is one of the easier wins available, and flagging it adds meaningful value without much additional lift. Working with business clients to review their banking arrangements and how they treat excess cash can reduce the burden associated with cash management, while giving a more holistic view across other areas including tax, dividend and pension planning.
Opening up the conversation around cash
The businesses in our research are not indifferent to how their cash is managed. The intent is there, but what is often missing is the structure, the visibility, and the trusted guidance to do something about it.
Accountants are in the best position to offer those advisory services. These findings provide an opportunity to open the conversation around cash management. Many businesses are missing out on the opportunity to make sure their cash holdings are diversified and earning better returns, while also making the best use of FSCS protection.
*Data based on businesses surveyed with more than one banking relationship.
Main image: Kate Toumazi is CEO of Insignis. Main video supplied by selamiozalp/Creatas Video via Getty Images